🌍 88.8 — Germany's mood beat every forecast
The Ifo business climate hit 88.8 in August against 87.2 expected — a fourth rise in a row and a year's high. Today: reading a survey against its forecast.
Compiled Tuesday, 25 August 2026, at about 10:30 am in Frankfurt (CEST, UTC+2). Index rows are final Monday closes, settled and cross-checked against two sources; currency, bond and oil rows are Tuesday-morning snapshots, still moving, and say so. The live paragraph beneath the table covers Tuesday so far.
German businesses just reported their best mood in a year, and nobody who was paid to guess saw it coming. The Ifo business climate index rose to 88.8 in August, against a consensus of 87.2 and 86.6 in July — Trading Economics carries the same 88.8 and 87.2. Monday's board, meanwhile, was as flat as a board gets, and the two facts belong in the same letter.
📊 The Dashboard — Monday, 24 August 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| STOXX 600 (pan-Europe) | 654.21 | ⚪ ≈ flat (+0.00%) | Final — Investing.com historical and Google Finance agree. Three hundredths of a point above Friday. Underneath the zero, chip and AI-infrastructure names fell ahead of Nvidia's results — Infineon and Siemens Energy about 3%, ASML 1% — while miners led on firmer gold and silver, and travel stocks rose as oil eased. Losers and winners cancelled to the decimal. |
| DAX (Germany) | 26,106.60 | 🔴 ▼ −0.11% | Final — Investing.com and Google Finance agree. Frankfurt carries Infineon and Siemens Energy, so the chip caution showed here first. Still above 26,000. |
| FTSE 100 (UK) | 10,854.32 | 🟢 ▲ +0.35% | Final — Investing.com and Google Finance agree. A fifth green day running, and Monday's strongest big board: London is where Europe's miners live, and metals rose. |
| CAC 40 (France) | 8,453.01 | 🔴 ▼ −0.37% | Rotation row, final — Investing.com and Google Finance agree. The weakest of the four, giving back Friday's gain exactly. |
| EUR/USD | ≈1.167 | ⚪ ≈ flat | Tuesday snapshot, still trading — 1.1666 this morning, within a whisker of Monday's level. The dollar index pushed through 98.90 on Monday; the euro held its ground against it. |
| GBP/USD | ≈1.364 | ⚪ ≈ flat | Tuesday snapshot, still trading — 1.3639 this morning, the same neighbourhood as yesterday. A quiet pair on a quiet day for UK data. |
| Bund 10Y yield | ≈3.25% | ⚪ ≈ flat | Tuesday snapshot — 3.25%, a fraction of a basis point higher, close to the 3.275% touched last week, the highest in fifteen years. Money markets price more than 40 basis points of further ECB tightening this year, with the first move fully priced for September. A stronger Ifo does nothing to talk that down. |
Tuesday, live: as of mid-morning the STOXX 600 is up about 0.2% near 655, with technology weakness easing as the market waits for Nvidia; the DAX is up about 0.2% and the FTSE 100 about 0.2%. Germany also got a second piece of good news: second-quarter GDP growth was revised up to 0.3% from 0.2%, led by a 2% rise in exports. Brent trades near $91, down about 1%, after Treasury Secretary Bessent's Monday-evening briefing: sanctions on about 60 entities, vessels and individuals, and secondary sanctions widened to digital assets, technology, gold, aviation and shipping. A large announcement, a small oil move. Snapshots, not closes; Tuesday's final board lands tomorrow.
What happened, in plain words
The Ifo index is a survey of German firms' mood (the Spotlight below explains it). Above 100 signals net optimism; below it, net pessimism — so 88.8 still describes a cautious country, and today's story is the direction and the surprise, not the level.
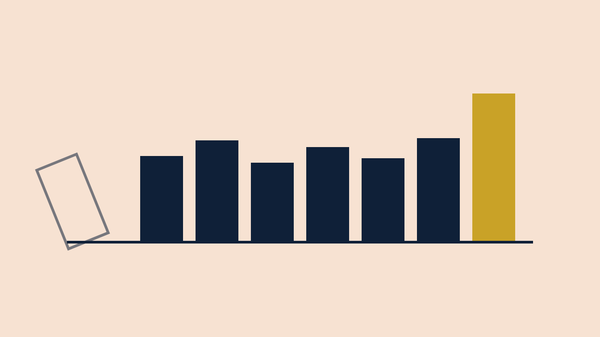
The direction: four rises in a row. The year's low was April, when the index fell to 84.4, its weakest since October 2022, as the Gulf conflict sent energy prices up. May, June, July and now August have each added to it, and 88.8 is the highest reading of 2026. The surprise: economists expected 87.2 — Commerzbank had pencilled in a dip to 86.0 — and the survey came in 1.6 points above the crowd. Both halves improved: firms rated current conditions at 88.5, up from 86.5, and expectations at 89.1, up from 86.8. That matters because a rise built only on expectations is hope, while a rise in the current-conditions half is firms describing the order books they already have.
One caveat travels with every survey: it measures what managers say, not what they ship. Friday's flash PMI said the same thing from a different questionnaire, and this morning's GDP revision put a hard number under both. When soft data and hard data point the same way, the direction is worth more than either alone.
⭐ Spotlight: 88.8 — the Ifo business climate, and the forecast next to it
Each month the Munich-based ifo Institute asks several thousand German firms two questions — how is business now, and how will it be in six months — and turns the answers into an index across manufacturing, services, trade and construction. It is watched because Germany is the euro area's largest economy, and because it arrives early: a manager's answer in August describes August, while official output data for August will not exist until October. The new reading skill today is that a survey number never travels alone — it is always printed beside a consensus, and the market reacts to the gap between the two, because the consensus was already in prices before the release. August's gap was +1.6 points (88.8 against 87.2); April's was −1.1 (84.4 against 85.5). Same gauge, same arithmetic, opposite surprises.
📈 Chart of the Day — the slump, then four rises in a row
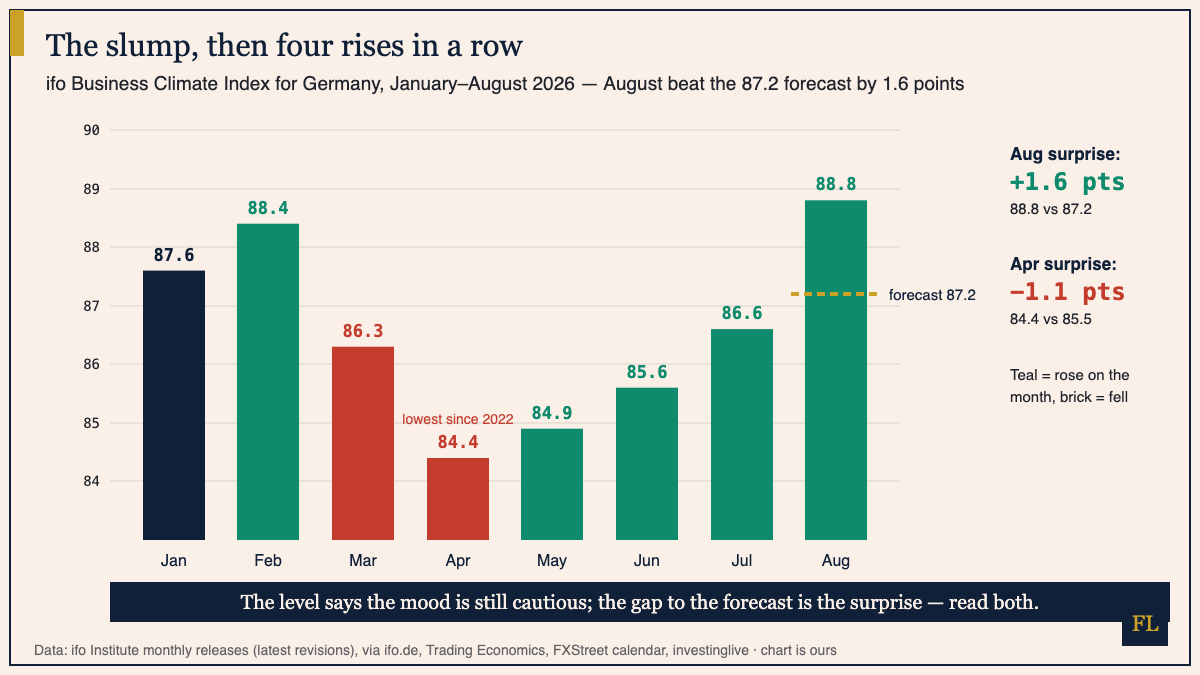
How to read this: read a survey chart twice. First the bars against each other — that is the mood's direction, and here it is a V: a two-month slide into April, then four steps back up. Then read the last bar against the dashed line — that is the surprise, and it is the only part the market did not already know on Tuesday morning. A bar that rises but lands below the dashed line is a disappointment dressed as an improvement; today's landed well above it. Bars carry the latest published revisions, so earlier months can differ slightly from their release-day figure.
📅 Tomorrow
Wednesday is quiet in Europe's own calendar — an ECB board speech from Piero Cipollone and a German bond auction — and heavy after Europe's close: US July PCE inflation, the second estimate of US second-quarter GDP, and Nvidia's results after the New York close. Europe's chip names sold off on Monday waiting for that last one; Thursday morning is when their verdict lands here. Thursday also brings Germany's GfK consumer climate at 8:00 am CET, the ECB's account of its July meeting, and the opening of the Fed's Jackson Hole symposium.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors — verify before relying on it. Sources: Investing.com historical (STOXX 600, DAX, FTSE 100, CAC 40); Google Finance (STOXX 600, DAX, FTSE 100, CAC 40, EUR/USD, GBP/USD); FXStreet economic calendar (Ifo); Trading Economics (Ifo, Bund yield, Brent, session notes); ifo Institute (series); investinglive (April Ifo, Q2 GDP revision); Newsquawk (Monday wrap, weekly calendar); Al Jazeera (Iran sanctions); NIM (GfK schedule); ECB (accounts schedule).
— The Editorial Team