🌎 Nasdaq −0.8% — chips fell hardest, two days before Nvidia reports
Chip stocks led Monday's slide ahead of Nvidia's results; a Treasury cash-account report eased yields; new sanctions on Iran, new tariffs on Canada.
Compiled Tuesday, 25 August 2026, about 7:00 a.m. in New York (Eastern Time), before the opening bell. Stock index rows are final Monday closes, cross-checked against two settled sources; bond yields, currencies and oil trade around the clock, so those rows are Tuesday-morning snapshots and labeled as such.
Chip stocks did the damage on Monday: the tech-heavy Nasdaq fell 0.8% while the Dow rose, as memory and AI-chip makers sold off two days before Nvidia reports.
📊 The Dashboard — Monday, 24 August 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| S&P 500 (500 big US firms) | 7,652.86 | 🔴 ▼ −0.3% | Final. Down 21.51 points; Investing.com's settled row agrees to the cent (−0.28%). A small red day: the chip slide was real, but most of the 500 barely moved. |
| Nasdaq Composite (tech-heavy) | 25,980.19 | 🔴 ▼ −0.8% | Final. Down 200.26 points (−0.76% settled) — Monday's worst big board, because this is where the chipmakers live. |
| Dow (30 blue-chip firms) | 53,417.16 | 🟢 ▲ +0.3% | Final. Up 140.15 points (+0.26% settled). Thirty old-economy names, few chips — the same day read green here. |
| Russell 2000 (2,000 smaller firms) | 2,995.08 | 🔴 ▼ −0.8% | Rotation row, final. Down 22.79 points (−0.76% settled), back below 3,000 but still +20.7% for the year, the best of the four. |
| US 10-year Treasury yield | ≈4.67% | ⚪ ▼ easing | Tuesday snapshot. Fell 4 basis points to 4.70% Monday on the Treasury cash-account report (below), and sat near 4.67% Tuesday morning; the 30-year eased to 5.23%. Lower yields are a tailwind stocks ignored on Monday. |
| Dollar index (DXY) | ≈99.0 | ⚪ ≈ flat | Tuesday snapshot. Steady near 99 after a small Monday gain on safe-haven demand as Washington moved to cut Iran off from the dollar system. |
| USD/CAD | ≈1.386 | ⚪ ▲ ≈+0.1% | Tuesday snapshot. Edged up to 1.3857 after Monday's tariff escalation — a mild loonie slip, not Monday's jump. A rising pair means a weaker Canadian dollar. |
| USD/MXN | ≈16.95 | ⚪ ≈ flat | Tuesday snapshot. 16.946, down 0.02% — the peso keeps its quiet strength, with Mexico's 6.50% policy rate still well above the Fed's. |
What happened, in plain words
Monday was a chip story wearing an index costume. Micron fell 5.8% and Nvidia 2.9%, with AMD and Broadcom down 3.5% and 2.6%; Yahoo Finance counted Nvidia's fall as a seventh straight decline. Two things sat behind it. First, a Bloomberg report that Nvidia's biggest customers have been told AI-server prices will rise more than 15% in many cases from early next year, because memory chips are getting expensive — good for Nvidia's revenue, awkward for everyone who buys from it. Second, the calendar: Nvidia reports Wednesday after the close, and its shares have fallen after six of the past eight reports. Some holders simply chose not to wait.
The bond market went the other way. CNBC reported, and Yahoo Finance relayed, that the Treasury may fund its enlarged bond buybacks from its General Account — the government's roughly $950 billion checking account at the Fed — instead of borrowing short-term to pay for them. The 10-year yield fell 4 basis points to 4.70% and the 30-year to 5.23%. Last week we said buybacks funded by new short-term bills mostly shuffle debt around; paying from cash on hand is a different animal, which is why the market moved on a report rather than a decision.
Two foreign-policy moves rounded out the day. Treasury Secretary Bessent launched "Operation Economic Outcast," sanctions on Iran's digital-asset, gold, aviation, technology and shipping links, warning that anyone laundering money for Tehran "will be removed from the U.S. dollar system." Oil fell rather than rose — Brent lost 2.4% Monday and near 3% more Tuesday to about $89.5, on signs of diplomatic progress and sanctions less severe than traders had feared. And Trump said tariffs on Canadian cars, trucks, parts and steel will rise to 50% on 1 January 2027, doubling the 25% auto rate; Canada's own retaliation still lands 8 September. The loonie barely moved on it — Saturday's tariffs had already been priced.
⭐ Spotlight: the chip index — 11,423
The Philadelphia Semiconductor Index (the "SOX") is a basket of 30 chip companies — designers, memory makers, and the firms that build the machines that etch them. On Monday its settled close was 11,423.2, down 2.7%; some wires printed a steeper mid-session drop, which is why we quote the settled row. Watchers track it because chips sit under every AI headline: when the SOX moves three times as much as the Nasdaq, as it did Monday, it tells you the selling was concentrated in one industry, not spread across technology. It is also a scale lesson — a 2.7% day that would be alarming for the S&P 500 is an ordinary Monday for a 30-name index of the market's most volatile industry.
📈 Chart of the Day — Monday, board by board
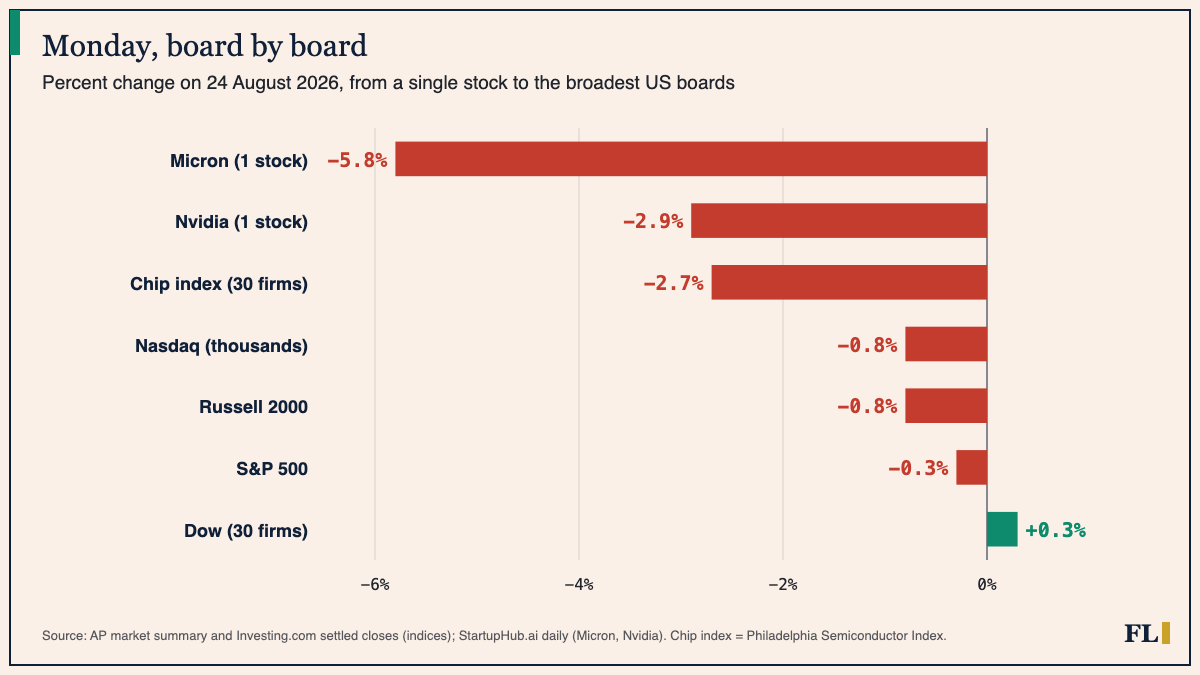
How to read this: read the labels before the bars. One stock, then 30 chip stocks, then thousands of Nasdaq names, then the broadest boards — and the bars shrink almost in step. That is diversification made visible: the wider the basket, the more one industry's bad day gets averaged away, until the Dow, with few chips inside it, shows green. The habit: when a headline says "stocks fell," ask which basket — the answer tells you whether it was a market day or an industry day.
📅 Tomorrow
Tuesday brings the month's read on the household mood: the Conference Board's consumer confidence index at 10:00 a.m. ET, after July's 90.8, alongside June home prices, July new-home sales and the Richmond Fed factory survey. Watch whether confidence slips again while spending stays firm — that gap has been the summer's puzzle. Then Wednesday stacks July PCE inflation, the second Q2 GDP estimate and durable goods at 8:30 a.m., and Nvidia after the close, ahead of Fed Chair Warsh's first Jackson Hole keynote Friday around 10 a.m. ET.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors — verify before relying on it. Sources: AP (Monday closes, via Barchart); Investing.com historical (S&P 500, Nasdaq, Dow, Russell 2000, SOX); Yahoo Finance live blog (24 Aug); StartupHub.ai AI stocks daily; Yahoo Finance / CNBC (Treasury General Account); Bloomberg via Yahoo (Nvidia prices); CBS News (Iran sanctions); AP via ABC7 (Canada tariffs); Trading Economics (10-year, DXY, USD/CAD, USD/MXN, Brent, calendar); FinancialJuice week ahead; Regards of Wall Street (Jackson Hole).
— The Editorial Team