🌎 S&P 500 +0.7% — one stock lifted the board; the average stock fell
Nvidia's 8.7% jump carried the S&P 500 up 0.7% while the equal-weight index fell 0.3% and ten of eleven sectors closed lower. Warsh speaks at 10 a.m. ET.
Compiled Friday, 28 August 2026, about 7:30 a.m. in New York (Eastern Time), before the opening bell. A 3-min read. Stock index rows are final Thursday closes, cross-checked against two settled sources; bond yields, currencies and oil trade around the clock, so those rows are Friday-morning snapshots and labeled as such.
The S&P 500 rose 0.7% on Thursday while the average stock inside it fell — one very large company did the lifting, and today’s issue is about how to see that in the numbers.
📊 The Dashboard — Thursday, 27 August 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| S&P 500 (500 big US firms) | 7,730.99 | 🟢 ▲ +0.7% | Final. Up 55.29 points; Investing.com’s settled quote agrees to the cent (+0.72%). +0.7% for the week so far and +12.9% for the year. |
| Nasdaq Composite (tech-heavy) | 26,541.35 | 🟢 ▲ +1.6% | Final. Up 411.16 points (+1.57% settled), the week’s best board. Nvidia rose 8.74% — 8.7% on AP’s count — and it is the Nasdaq’s heaviest member too. |
| Dow (30 blue-chip firms) | 53,569.44 | 🟢 ▲ +0.2% | Final. Up 105.56 points (+0.20% settled). The Dow weights by share price, not company size, so the lift barely reached it; +0.5% on the week. |
| Russell 2000 (2,000 smaller firms) | 3,015.67 | 🟢 ▲ +0.3% | Rotation row. Investing.com’s settled row prints 3,015.67 (+9.77 points, +0.33%); AP’s closing-bell story printed 3,014.34 (+0.3%). They differ by 1.3 points and agree on the move; we print the settled row. −0.1% on the week, +21.5% for the year. |
| US 10-year Treasury yield | ≈4.69% | 🔴 ▲ edging up | Friday snapshot. About 4.69%, up roughly 2 basis points into the Fed chair’s speech; the 2-year sits near 4.24%, the 30-year near 5.21%. |
| Dollar index (DXY) | ≈99.2 | ⚪ ≈ flat | Friday snapshot. 99.2, barely moved for a fifth morning, waiting for the same speech as everyone else. |
| USD/CAD | ≈1.385 | ⚪ ≈ flat | Friday snapshot. About 1.385 ahead of Canada’s second-quarter GDP at 8:30 a.m. ET. A falling pair means a stronger Canadian dollar; a rising one, weaker. |
| USD/MXN | ≈16.96 | ⚪ ▼ ≈−0.1% | Friday snapshot. About 16.96, the peso firm near this week’s two-year high; Mexico’s 6.50% policy rate against the Fed’s 3.50–3.75% is the standing reason. |
What happened, in plain words
Two measurements of the same 500 companies disagreed on Thursday. The S&P 500 you see quoted counts each company in proportion to its market value, and it rose 0.72%. The equal-weight version — the same 500 names, each counted the same — fell 0.30% (Google Finance agrees, via the Invesco fund that tracks it). Ten of the eleven sectors closed lower: technology +3.4%, consumer staples −1.5%, health care −1.1%, consumer discretionary −1.0%. AP put it plainly: Nvidia “more than offset drops for the majority of the stocks within the S&P 500”. At about $5.5 trillion of market value on Motley Fool’s count, it is the index’s largest weight, so an 8.7% move in one member outweighed small declines in hundreds of others.
The reason was Wednesday night’s results: revenue of $96.2 billion, a $108 billion forecast for this quarter, and a 70% growth call for fiscal 2028. In Thursday’s regular session the shares rose 8.74%. Software joined in. Salesforce reported revenue of $11.35 billion against $11.32 billion expected, up 11%, raised its full-year outlook, and its chief executive told analysts “this nonsense of this SaaSpocalypse, I think it is time for it to stop”. The shares closed up 22.58% at $252.05; ServiceNow rose 10.05%, CrowdStrike 20.5% and Okta 28.6%. All of it sits inside technology, the one sector that rose.
The morning’s data pointed the other way from the boards. First-time jobless claims fell to 203,000 in the week to 22 August, down 4,000 and below the 208,000 forecast; the four-week average is 205,500, and continuing claims fell to 1.778 million. Few people are being let go. But the goods trade deficit widened to $118.8 billion in July from $101.4 billion — the largest since March 2025 — as exports fell 2.9% to $199.4 billion, the lowest since January, and imports rose 3.7% to $318.2 billion. Imports count against GDP, so a wider deficit subtracts from the next estimate. Trading Economics reads futures at about 65% odds of no change in September, with December-hike odds above 70%. The index rose on one company’s numbers, not on the economy’s.
⭐ Spotlight: the equal-weight S&P 500 — −0.3%
Take the same 500 companies and give each one a 0.2% share, regardless of size; that is the equal-weight S&P 500, and the Invesco fund that tracks it (ticker RSP) is how most people watch it. Watchers use it as “the average stock”: when it rises with the ordinary index, gains are broad; when the ordinary index rises and this one falls, as on Thursday (+0.72% against −0.30%), the gain is concentrated in a few large names. Both readings are true; a one-day gap of a point describes who did the lifting and forecasts nothing.
📈 Chart of the Day — the board and the average stock
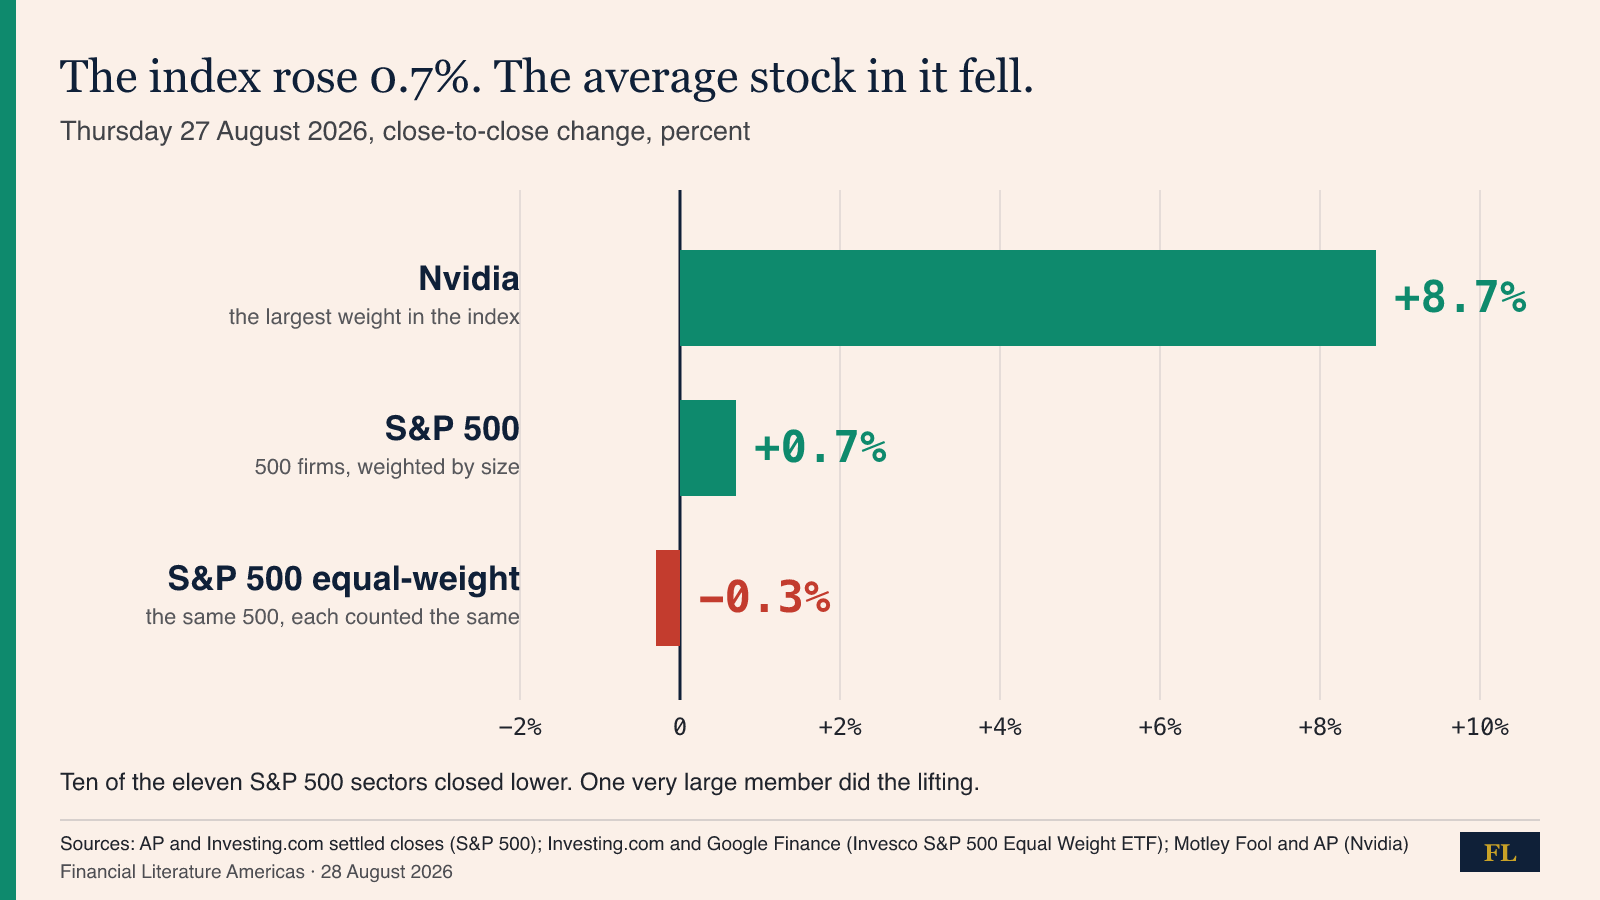
How to read this: read the gap between the two S&P 500 bars before you read either one. The top bar explains the gap: a company that is the largest weight in the index moved almost nine points, so the index could rise while most of its members did not. When a headline index moves on one stock’s news, find the equal-weight figure; if the two bars point different ways, the day’s story belongs to one company, not to “the market.”
📅 Tomorrow
At 8:30 a.m. ET Friday Statistics Canada reports second-quarter GDP: the consensus is 3.4% annualized (a Reuters poll of economists agrees) after a slight first-quarter decline; watch USD/CAD around the print. At 10 a.m. ET Fed Chair Warsh gives his first Jackson Hole keynote — MNI and Newsquawk, both dated 20 August, agree on the time. Listen for whether he addresses the 15–16 September meeting at all, or describes a framework instead. Next week: ISM manufacturing and job openings on Tuesday, the Beige Book on Wednesday, ISM services on Thursday and the August jobs report on Friday, 4 September; US markets close Monday, 7 September, for Labor Day. Brent sits near $88.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors — verify before relying on it. Sources: AP (Thursday closes, via The Epoch Times); Investing.com settled quotes (S&P 500, Nasdaq, Dow, Russell 2000, equal-weight ETF); Google Finance (RSP); Neil Sethi, Markets Update 27 Aug; Motley Fool (Nvidia), Motley Fool (Salesforce), Motley Fool (Salesforce results); Yahoo Finance live blog; Reuters via Yahoo Finance (claims, trade); Investing.com calendar; Trading Economics (claims, goods trade, 10-year, DXY, USD/CAD, USD/MXN, Brent, Canada GDP); Narcity (Canadian Press); MNI, Newsquawk; Schaeffer’s week ahead; NYSE calendar.
Forwarded this by a friend? Subscribe here. Found it useful? Forward it to one person who'd want it.
— The Editorial Team