🌍 $96.2bn — Nvidia's quarter reached Europe's chips, not its board
Nvidia's record $96.2bn quarter lifted Europe's chipmakers on Thursday morning while the STOXX 600 sat flat at 656.41. Today: how index weight works.
Compiled Thursday, 27 August 2026, at about 10:30 am in Frankfurt (CEST, UTC+2) — a 5-min read. Index and bond rows are final Wednesday closes, cross-checked against two sources; currency rows are Thursday-morning snapshots, still moving, and say so.
Nvidia reported a record $96.2 billion quarter overnight, and by mid-morning Europe's chipmakers were up 2–4% while the STOXX 600 sat a tenth of a percent below flat. Both are true at once; the reason is a number few readers have looked up: how much of the index technology is.
📊 The Dashboard — Wednesday, 26 August 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| STOXX 600 (pan-Europe) | 656.41 | ⚪ ≈ flat (−0.01%) | Final — Investing.com historical and Google Finance agree; a third wire printed the same 656.41. Underneath: Deutsche Bank up 4.3%, SAP down about 3% — cancelled to the decimal. |
| DAX (Germany) | 26,285.96 | 🟢 ▲ +0.08% | Final — Investing.com and Google Finance agree on the level (one wire printed +0.19%; we use the settle pair). Frankfurt carries both Deutsche Bank and SAP. |
| FTSE 100 (UK) | 10,878.12 | 🔴 ▼ −0.07% | Final — Investing.com and Google Finance agree. The six-day green run ended by eight points. |
| CAC 40 (France) | 8,462.39 | 🟢 ▲ +0.27% | Rotation row, final — Investing.com and Google Finance agree. Consumer products led the session. |
| EUR/USD | ≈1.165 | 🔴 ▼ small | Thursday snapshot, still trading — 1.1654 at 8:22 am UTC, from about 1.168 yesterday. The dollar index reached 99.14 after the US inflation print. |
| GBP/USD | ≈1.359 | 🔴 ▼ small | Thursday snapshot, still trading — 1.3588 this morning, the pair's softest level this week; 1.3594 was Wednesday's support. |
| Bund 10Y yield | 3.23% | 🟢 ▲ +2.3 bp | Wednesday close, final — Investing.com has 3.2267%, from 3.2033% on Tuesday; Trading Economics reads 3.24% this morning. Half of Tuesday's oil-driven drop given back. |
Thursday, live: mid-morning the STOXX 600 is at 655.6, down 0.1%; the DAX is up 0.2%, the FTSE 100 down 0.5% and the CAC 40 down 0.3%. The chip row: ASML +1.8%, ASM International +2.7%, STMicroelectronics +4.0%, Infineon +2.3%, SAP +1.2% (Google Finance, about 10:10 am). Energy majors and miners are lower; Brent trades below $87, a fourth session down after a $86.94 settle. Nvidia is indicated about 7% higher pre-market. Snapshots, not closes.
What happened, in plain words
The quarter first. Nvidia's revenue for the three months to 26 July was $96.2 billion, up 106% from a year earlier; data-centre revenue alone was $89.0 billion; the company guided the next quarter to $108 billion — Yahoo Finance carries the same figures. Europe does not make Nvidia's chips, but it makes the machines that make them (ASML, ASM International) and some of the chips around them (STMicro, Infineon). A customer buying more means its suppliers sell more, so their shares rose at the open.
Now the index. Wednesday's board was flat because two large German names pulled in opposite directions: Deutsche Bank rose 4.3% on the first day of a new €500 million buyback, the first funded from current-year profit, and SAP fell about 3% after a US software company's weak forecast and a broker downgrade. Thursday's board is flat for a different reason: the stocks that jumped are, together, a small piece of the index — the Spotlight's concept.
The macro backdrop moved the currencies more than the shares. US July PCE inflation — the Fed's preferred gauge — held at 3.7% year on year, with the monthly rise at 0.2% against 0.1% expected; core was in line at 3.3%. A hotter number argues for a Fed that stays firm, so the dollar index climbed to 99.14 and the euro and pound slipped. Germany got its second good survey of the week: GfK consumer climate for September rose 2.8 points to −26.6, against a consensus of −29.6, its least pessimistic reading since March, on a 16-point jump in income expectations. Still deeply negative — but, like Tuesday's Ifo, the direction beat the forecast.
⭐ Spotlight: index weight — why 600 stocks don't count the same
The STOXX 600 is not an average of 600 prices. Each company counts in proportion to its market value, so a 1% move in ASML — 4.1% of the index, the largest single weight — moves the index about 0.04 points of a percent, while a 1% move in the smallest member moves it by nothing you could see. The ten biggest names are 19.5% of the whole; technology as a group is about 9%. Compare New York: information technology is 36.5% of the S&P 500, four times Europe's share. The same Nvidia headline has four times the leverage on the US index that it has on ours — before anyone forms an opinion. When Europe's chips rise 2–4% and the board moves a tenth of a percent, nothing is being ignored; the arithmetic is doing what it is built to do. (The two indices use different classification systems, ICB and GICS — read the comparison as scale, not to the decimal.)
📈 Chart of the Day — technology is a third of New York's index and a tenth of Europe's
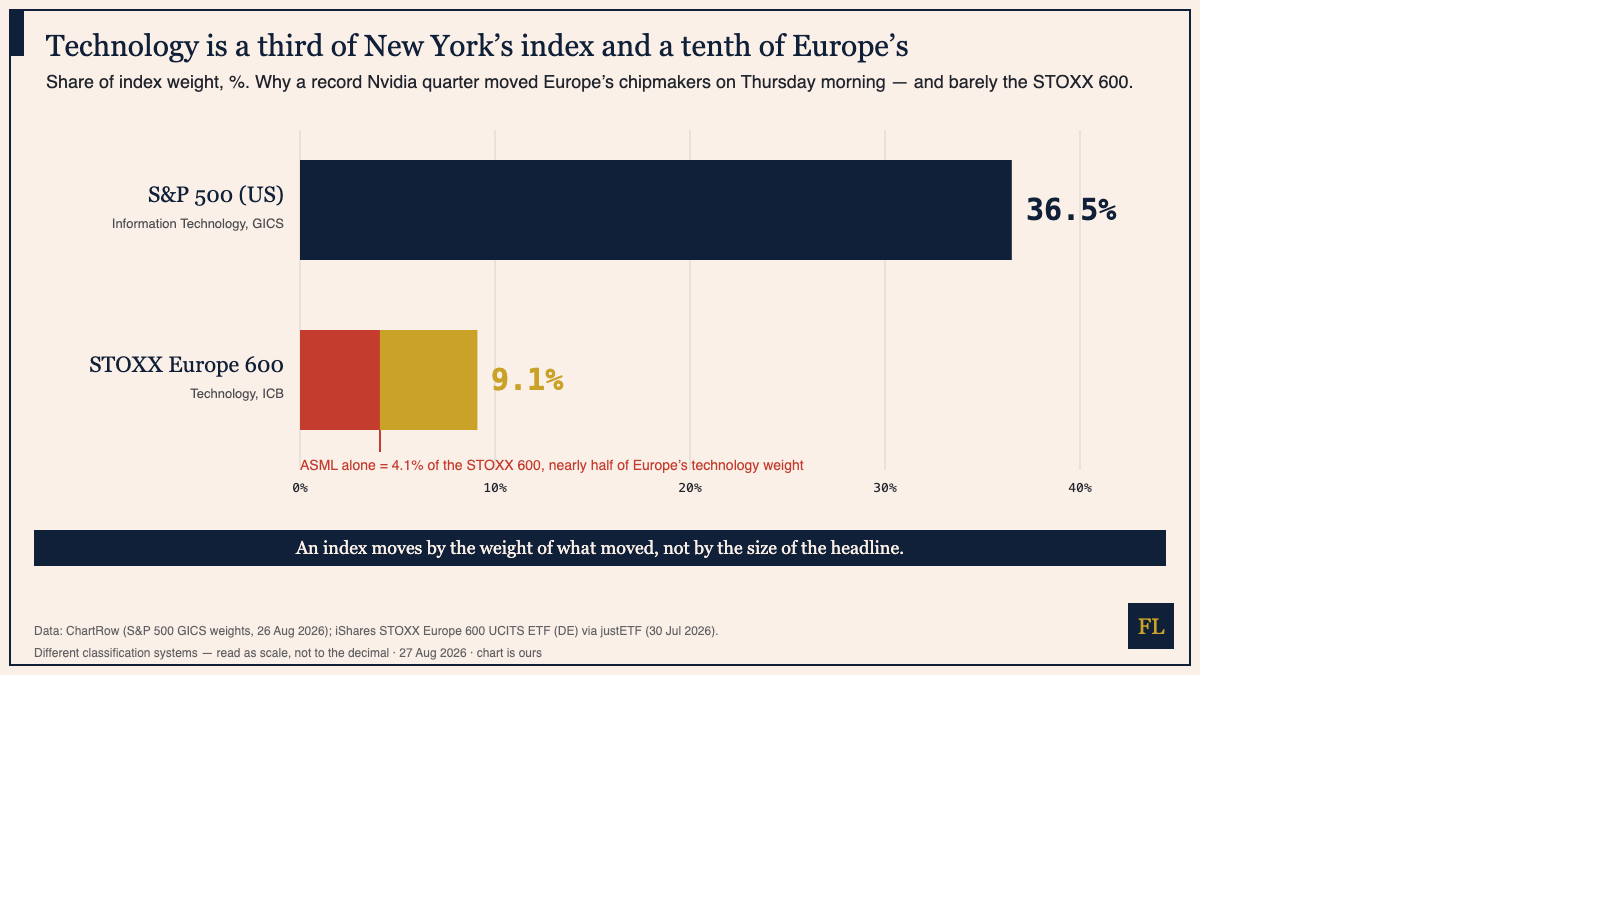
How to read this: a weight chart answers one question before any news arrives — how much of the index can this story touch? Read the bar, then the red segment: nearly half of Europe's technology weight is one company, so "European tech rallied" often means "ASML rallied". Then multiply a sector's move by its weight to get its contribution: Thursday's chips, up roughly 3% on a 9% weight, add about 0.3 points of a percent; energy and miners, down on a similar combined weight, take it back. That is how a rally and a flat index share a morning.
Yesterday we followed an oil price into the Bund yield; last week, the gap between US and German ten-year yields. Today's lesson is structural — true tomorrow too; the archive keeps the earlier ones.
📅 Tomorrow
Still today: the ECB publishes the account of its 22–23 July meeting at 1:30 pm CET , and US weekly jobless claims at 2:30 pm. Friday: French and Spanish flash August inflation, German unemployment, Schnabel, and Fitch's review of France. Then the week's main event: Fed Chair Warsh's first Jackson Hole keynote, about 10:00 am Eastern (4 pm in Frankfurt; two calendars agree on the hour), 19 days before the 16 September FOMC. Watch EUR/USD in the minutes after he starts.
Forwarded this by a friend? Subscribe here. Found it useful? Forward it to one person who'd want it.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors — verify before relying on it. Sources: Investing.com historical (STOXX 600, DAX, FTSE 100, CAC 40, Brent, Germany 10Y); Google Finance (STOXX 600, DAX, FTSE 100, CAC 40, EUR/USD, GBP/USD, single stocks, Nvidia); Trading Economics (Bund, Brent, sessions, GfK); Newsquawk (Wednesday wrap, weekly calendar); Nvidia (Q2 FY2027 results); Yahoo Finance (Nvidia, PCE); Deutsche Bank (buyback); NIM (GfK consumer climate); ChartRow (S&P 500 sector weights); justETF (iShares STOXX Europe 600 breakdown); ECB (accounts); Babypips, Regards of Wall Street (Jackson Hole).
— The Editorial Team