🌎 55.4 — services grew faster; the jobs part of the same gauge shrank
The services survey rose to 55.4 on its best activity reading since 2022, while its own employment component stayed below 50. Waller hinted at a hold.
Compiled Friday, 4 September 2026, about 7:25 a.m. in New York (Eastern Time), before the opening bell. A 4-min read. Stock index rows are final Thursday closes; yields, currencies and oil trade around the clock, so those rows are Friday-morning snapshots.
Yesterday's answer: B — because a currency pair prices the difference between two rates and the expected path of that difference; on Wednesday both rates stood still, so only what traders expected of them moved.
One Federal Reserve governor said he could wait, and the American boards had their best day in a month: the S&P 500 rose 1.06%, the Dow added 624 points, and the odds of a rate rise on 16 September fell to roughly a coin flip on a morning when the August services survey grew at its fastest in years with its own hiring gauge still shrinking.
📊 The Dashboard, Thursday, 3 September 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| S&P 500 (500 big US firms) | 7,747.71 | 🟢 ▲ +1.06% | Final. Up 81.11 points, the best session since 4 August. |
| Nasdaq Composite (tech-heavy) | 26,584.06 | 🟢 ▲ +1.40% | Final. Up 366.23 points. Lower yields help the companies whose profits sit furthest in the future. |
| Dow (30 blue-chip firms) | 53,686.11 | 🟢 ▲ +1.18% | Final. Up 624.16 points. |
| Russell 2000 (2,000 smaller firms) | 2,968.27 | 🟢 ▲ +0.51% | Rotation row. Up 15.10 points, the day's laggard after leading on Wednesday. |
| US 10-year Treasury yield | ≈4.77% | ⚪ ≈ steady | Friday snapshot (Investing.com). Thursday it closed at 4.762%, down from about 4.79%; the 2-year is near 4.35%. |
| Dollar index (DXY) | ≈99.1 | ⚪ ≈ steady | Friday snapshot. Thursday's close was 99.00, down from 99.55 on Wednesday. |
| USD/CAD | ≈1.380 | ⚪ ≈ steady | Friday snapshot, from 1.3794 at Thursday's close. Canada publishes its own August jobs figures at 8:30 a.m. ET. |
| USD/MXN | ≈16.90 | 🟢 ▼ peso firm | Friday snapshot, from 16.9041, within a whisker of the peso's strongest level against the dollar in a year. |
What happened, in plain words
Two Fed voices are now pulling in opposite directions. Chair Kevin Warsh told Jackson Hole a week ago that prices come first, and traders moved to price a rate rise this month. On Thursday, Governor Christopher Waller told a Reuters event in Washington that recent data "suggest we are finally seeing some signs of disinflation" and that, if that continues over the next two weeks, "I would be inclined to support holding the target for the federal funds rate at its current setting." Futures repriced within minutes, from about two-thirds odds of a rise to roughly a coin flip; by Friday morning Investing.com's rate monitor had the 16 September meeting at 50.4% for a rise and 49.6% for no change. The data that morning pushed both ways at once: services grew faster than expected while the prices service firms pay reached a four-year high, jobless claims were 206,000 against 205,000 expected, and the July trade gap widened 24.4% to $88.6 billion, the widest since March 2025, as imports of computers rose $6.9 billion and computer accessories $6.6 billion.
⭐ Spotlight: the ISM Services PMI, 55.4
Every month the Institute for Supply Management asks purchasing managers at service companies whether a list of things got better, worse or stayed the same, and turns the answers into diffusion indexes where 50 means the two camps are the same size. The services survey covers the industries where most Americans actually work, which is why it carries more weight than the factory version that ran on Tuesday. August's headline was 55.4%, up 1.3 points from July's 54.1% and the 26th month in a row above 50. Underneath it, business activity reached 61.7%, its highest since November 2022, and new orders 60.9%, the highest since February 2023. Prices came in at 72.6%, above 70 for the fifth time in six months, with chair Steve Miller reporting that "tariffs and the Middle East conflict returned as the most cited issues impacting respondents' supply chains." Employment was 47.8%, contracting for a second straight month, though the share of firms cutting staff fell from 19% in July to 17.1% in August. ISM's own rule is that a reading above 48.1% is consistent with the whole economy expanding, which by this measure it has now done for 75 months.
📈 Chart of the Day: what 55.4 is made of
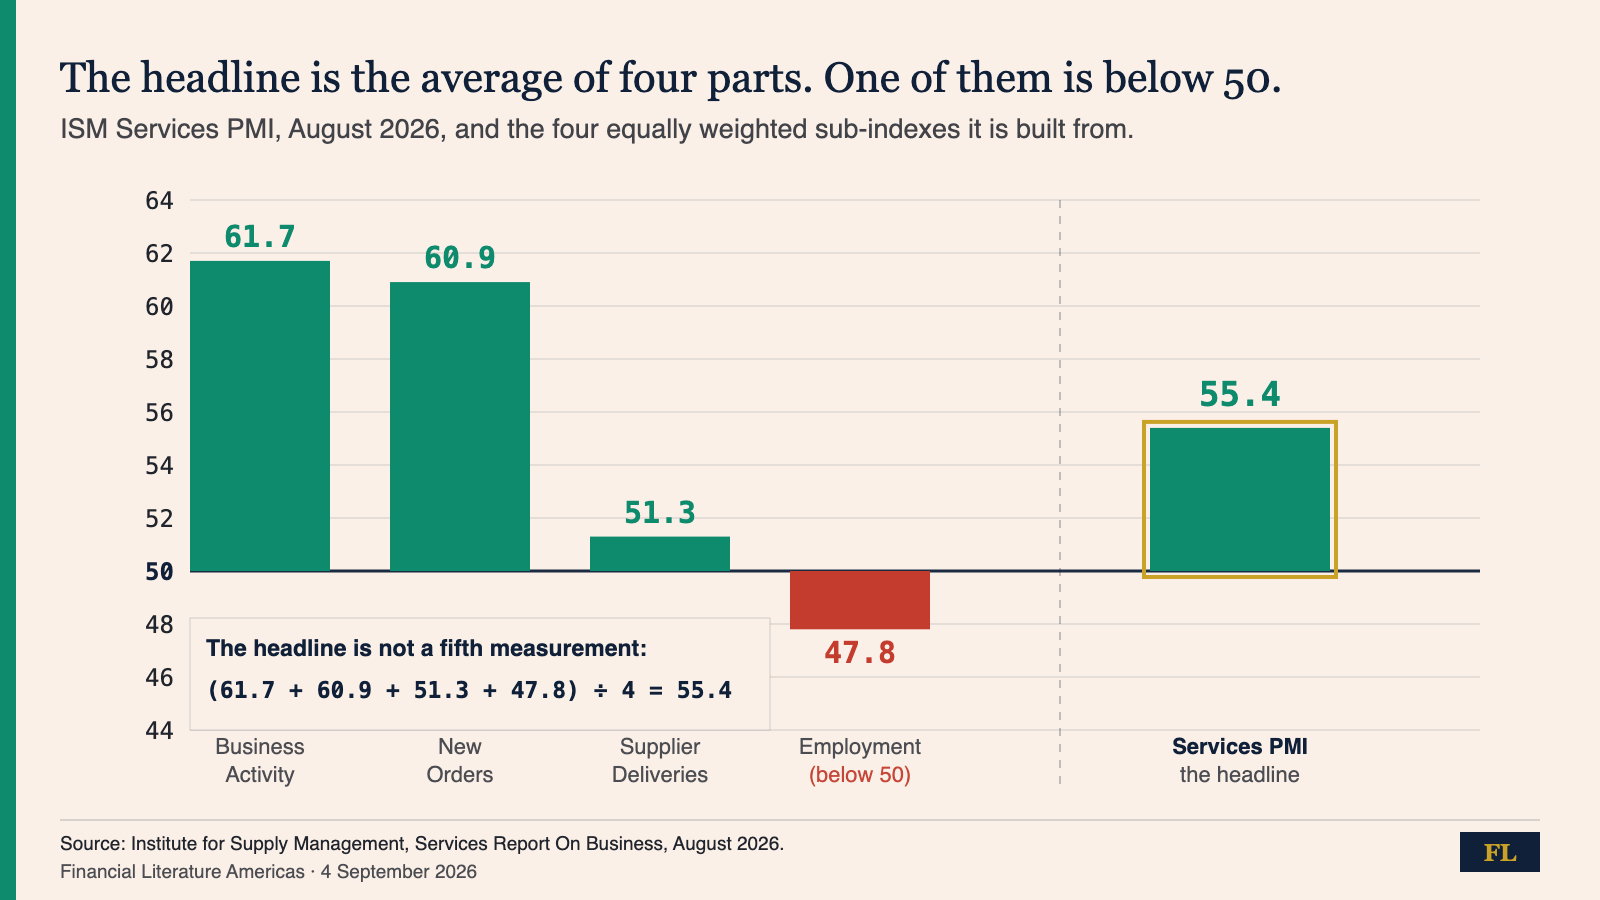
How to read this: read the parts before you read the headline. The Services PMI is not a measurement of its own; it is the plain average of four sub-indexes with equal weights, so a strong headline can carry a weak part inside it, and August's did. Once you know that, ask which component moved, because the same headline means different things depending on the answer: a lift from new orders is demand arriving, while a lift from supplier deliveries is deliveries getting slower, which the index scores as a positive but a shopper would not. The same arithmetic sits behind the factory survey and every other diffusion composite you will meet.
📅 Tomorrow
Today at 8:30 a.m. ET, the August employment report. Collectors put the consensus for jobs added near 56,000 and 53,000 after July's fall of 23,000, with the unemployment rate expected to hold at 4.1%. Canada publishes its own August labour force survey at the same minute, where a Reuters poll looks for about 15,000 jobs and an unchanged 6.4%. US markets are closed on Monday, 7 September, for Labor Day. The inflation data Waller said he is waiting on lands the week after: producer prices on Thursday 10 September and the August consumer price index on Friday 11 September, both at 8:30 a.m. ET, five days before the Fed decides on 16 September. The next issue reads the payroll report the way today's read the survey, by its parts.
One question. Today's chart showed a Services PMI of 55.4 built from business activity 61.7, new orders 60.9, supplier deliveries 51.3 and employment 47.8. Which reading is right? A: a headline of 55.4 means every part of the services survey grew in August. B: the headline is the equally weighted average of those four, so it can sit well above 50 while one of its own components contracts, which is what happened. C: employment at 47.8 means service firms cut 2.2% of their staff during August.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors, so verify before relying on it. Sources: ISM Services Report On Business; Trading Economics; S&P 500; Nasdaq; Dow; Russell 2000; Google Finance; Waller speech; Fed rate monitor; BEA trade release; jobless claims; BLS release schedule; FOMC calendar.
This follows yesterday's issue, the Bank of Canada held and changed one sentence, and Wednesday's, fewer factories grew in August.
Forwarded this by a friend? Subscribe here. Found it useful? Forward it to one person who'd want it.
— The Editorial Team