🌎 89.4 — consumers rated today better, tomorrow worse
Confidence hit a seven-month low while the 'present' half jumped; stocks rose anyway as oil and yields fell. PCE at 8:30, Nvidia after the close.
Compiled Wednesday, 26 August 2026, about 7:00 a.m. in New York (Eastern Time), before the opening bell. A 3-min read. Stock index rows are final Tuesday closes, cross-checked against two settled sources; bond yields, currencies and oil trade around the clock, so those rows are Wednesday-morning snapshots and labeled as such.
Consumer confidence slipped to 89.4, its lowest since January — yet the half of the survey that asks about today jumped, and stocks rose anyway as oil and bond yields fell for a second day.
📊 The Dashboard — Tuesday, 25 August 2026 (closes)
| Gauge | Level | Move | What this means |
|---|---|---|---|
| S&P 500 (500 big US firms) | 7,677.28 | 🟢 ▲ +0.3% | Final. Up 24.42 points; Investing.com's settled row agrees to the cent (+0.32%). Back within reach of the record set earlier this month, and +12.2% for the year. |
| Nasdaq Composite (tech-heavy) | 26,151.30 | 🟢 ▲ +0.7% | Final. Up 171.11 points (+0.66% settled) — Tuesday's best board, recovering most of Monday's chip slide. |
| Dow (30 blue-chip firms) | 53,577.40 | 🟢 ▲ +0.3% | Final. Up 160.24 points (+0.30% settled), a third straight gain. One wire printed 53,579.94; the settled row and AP agree on 53,577.40, so that is what we print. |
| Russell 2000 (2,000 smaller firms) | 3,010.02 | 🟢 ▲ +0.5% | Rotation row, final. Up 14.94 points (+0.50% settled), back above 3,000 and still +21.3% for the year, the best of the four. |
| US 10-year Treasury yield | ≈4.65% | ⚪ ▼ easing | Wednesday snapshot. Fell 6 basis points to 4.63% Tuesday as oil slid, with the 30-year at 5.17%; about 4.65% Wednesday morning ahead of the inflation print. Two days of falling yields — the tailwind stocks ignored Monday, they used Tuesday. |
| Dollar index (DXY) | ≈99.0 | ⚪ ≈ flat | Wednesday snapshot. Steady near 99 for a third morning; the dollar is waiting for the same two things everyone is — inflation at 8:30 and Friday's Fed speech. |
| USD/CAD | ≈1.387 | 🟢 ▲ ≈+0.2% | Wednesday snapshot. Up to about 1.387 after Ottawa confirmed retaliatory tariffs of 15–50% on roughly $20 billion of US goods from 8 September. A rising pair means a weaker Canadian dollar. |
| USD/MXN | ≈16.93 | ⚪ ▼ ≈−0.1% | Wednesday snapshot. 16.93, the peso at its strongest in over two years — the 6.50% Mexican policy rate against the Fed's 3.50–3.75% keeps money content to wait in pesos. |
What happened, in plain words
The headline said the mood fell; the survey said something more interesting. The Conference Board's index slipped 0.8 points to 89.4, a second monthly decline and the weakest since January. But the index is a blend of two halves, and they went opposite ways: the Present Situation half — how consumers rate business and jobs right now — rose 6.8 points to 121.2, its first improvement in four months, while the Expectations half — the next six months — fell 5.8 points to 68.2. More people called jobs "plentiful" (27.0%, up from 24.4%) and fewer called them "hard to get" (19.5%, down from 21.7%). In the same breath, households said they expect 5.8% inflation over the coming year, up from 5.6%, and mentioned prices, energy, conflict and trade more often than in July. Today feels fine; tomorrow looks expensive — that is the whole print.
Housing supplied the harder number. New single-family home sales fell 10.5% in July to a 607,000 annual rate, the lowest since January and below the 620,000 economists expected, with the median price down to $393,800 and 30-year mortgage rates near 6.77%. Only 5.2% of consumers in the confidence survey plan to buy a home within six months, down from 6.5% — the two reports agree with each other.
Stocks looked past both because the bond market did. Brent crude fell 3.6% Tuesday, a third day of declines that has carried it to about $86 Wednesday morning, on signs of a Gulf shipping corridor and Iran sanctions that landed softer than feared. Cheaper oil means less inflation ahead, so yields fell, so stocks rose — the chain we drew last week when a gloomy Michigan survey met rising yields, now running in reverse. Inside the boards: Nvidia rose 2% to end a seven-day losing streak a day before it reports; Moderna jumped about 14% on a cancer-vaccine readout; and Dick's Sporting Goods fell 30% after cutting its full-year guidance — the day's reminder that one company's number can be a market-sized event for its own holders and a rounding error for the index.
⭐ Spotlight: the Expectations Index — 68.2
The Conference Board asks about 3,000 households two kinds of questions: how things are, and how they will be in six months for income, business and jobs. The second set becomes the Expectations Index. Watchers follow it because it is the forward half — and because the Board itself notes that a reading below 80 has often preceded a recession within a year. It has sat below that line for months (July was 74.0), which is the scale lesson: a threshold that stays crossed for a long stretch is a mood reading, not a countdown. Tuesday's 68.2 tells you households' outlook darkened sharply in one month; it does not tell you what the economy will do, and neither do we.
📈 Chart of the Day — one index, two halves
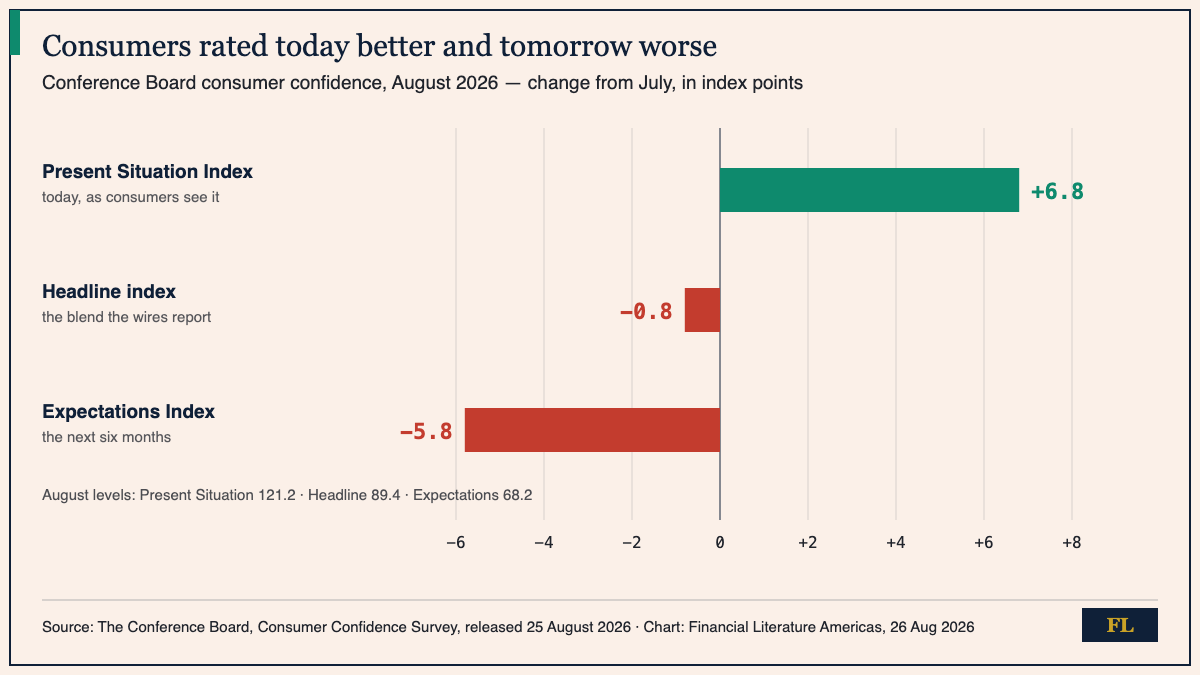
How to read this: whenever a headline index "barely moves," look for its parts before you accept the story. Here the −0.8 in the middle is an average of a +6.8 and a −5.8, which is not a small change at all — it is two large ones cancelling. The habit: a composite hides direction; the components hold it. Yesterday's chart made the same point with stock boards; today the survey does it with moods.
📅 Tomorrow
Wednesday is the week's data peak. At 8:30 a.m. ET the July PCE inflation report lands — the Fed's preferred gauge — with core prices expected at +0.2% on the month and 3.3% on the year, alongside the second estimate of Q2 GDP and July durable-goods orders. Watch the core monthly figure: futures now price only a 38% chance of a September hike, down from 55% a month ago, and a hot print would push that back up. After the close, Nvidia reports, with analysts looking for revenue of about $92.2 billion and $2.09 a share; we walked through why chips fell into it in yesterday's issue. Then Jackson Hole opens Thursday, with Fed Chair Warsh speaking Friday around 10 a.m. ET.
We explain; we never advise. Nothing here is investment advice.
Financial Literature is for educational and informational purposes only. Nothing here is investment, financial, legal, or tax advice, or a recommendation to buy or sell any security. Content is impersonal and not tailored to any individual. Data may contain errors — verify before relying on it. Sources: AP (Tuesday closes, via The Epoch Times); Investing.com historical (S&P 500, Nasdaq, Dow, Russell 2000); The Conference Board (August release); Quartz via Yahoo Finance (confidence detail); Reuters via GV Wire (new-home sales); Yahoo Finance live blog (25 Aug); Trading Economics (10-year, DXY, USD/CAD, USD/MXN, Brent, calendar); FXStreet (PCE preview, 26 Aug); Kiplinger (Nvidia expectations); Regards of Wall Street (Jackson Hole).
Forwarded this by a friend? Subscribe here. Found it useful? Forward it to one person who'd want it.
— The Editorial Team